
 617+ Lawyers are online

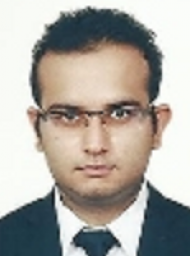
Advocate Rishabh Jain
 Verified

 4.7 |
5+
user ratings
 Alaknanda,
Delhi
 11 years Experience
Advocate Rishabh provides services in various fields of Cheque Bounce Matters, Consumer related Matters, Wills / Trusts Matters, Corporate Matters, Civil Matters and drafting and vetting of various agreements and documents.
Advocate Rishabh enrolled with the Bar Council of Delhi in 2015. He is also a member of Delhi High Court Bar Association.
Practice Areas
Civil
Documentation, Corporate, Breach of Contract, NCLT, Bankruptcy / Insolvency, Media and Entertainment
Wills / Trusts, Succession Certificate
Property, RERA
Cheque Bounce
Litigation
High Court
Courts
- Board for Industrial and Financial Reconstruction
- Bombay High Court
- Delhi High Court
- District Court, Patiala House
- District Court, Tis Hazari
- District Forum Central, Kashmeri Gate
- Intellectual Property Appellate Board (IPAB), Chennai
- National Green Tribunal (NGT)
- Punjab and Haryana High Court
- Punjab and Haryana High Court
Recently Contacted Lawyers in Delhi
Advocate Bhawana Pandey
4.8 Jangpura Extension,
Delhi
9 years Experience
Advocate Rajesh Rai
4.7 Sector-19, Dwarka,
Delhi
26 years Experience
Advocate Vijay Tangri
4.7 Saket,
Delhi
27 years Experience
Advocate Deepti Dogra
4.8 Pitampura,
Delhi
19 years Experience
Advocate Jia Kapur
4.6 Jangpura Extension,
Delhi
8 years Experience
Advocate Yuganshu Sharma
4.7 Lawrence Road, Keshav Puram,
Delhi
9 years Experience
Advocate Wg Cdr Ajit Kakkar (Retd)
4.8 Dwarka,
Delhi
26 years Experience
Advocate Prashant Vaxish
4.9 Lajpat Nagar 1,
Delhi
8 years Experience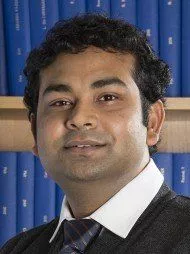
Advocate Nischal Arvind Singh
4.9 Hauz Khas Enclave,
Delhi
14 years ExperiencePopular Reviews
There are no reviews yet for Advocate Rishabh Jain. Please consult the lawyer through LawRato if you wish to leave a review.
Questions Answered by Advocate Rishabh Jain (50+ answers)
Q: How to transfer property from mother to daughter in gift deed ?
Mother wants to give her property to her daughter in gift deed ,can mother gift property to daughter ?what is the procedure?
Advocate Rishabh Jain answered
The title transfer can be performed only on the registered property. At least two witnesses should attest in the gift deed agreement. Usually the number of witnesses changes from place to place. After the payment of stamp duty and transfer duty charges, the property can be registered.
Q: How to file bankruptcy in india ?
I m unemployed and I have a debt of credit card ₹2 lakhs. So I would like to file a bankruptcy Petition. how to declare bankruptcy yourself in india ?
Advocate Rishabh Jain answered
The debtor (borrower), through his legal advisor, has to file a petition to the concerned insolvency court to declare him insolvent. He can do this if he is unable to pay his debts when due, when he is under arrest or imprisonment in execution of the decree of any court for the payment of money, or when an order of attachment is subsisting against his property.Similarly a creditor, who has a decree or an award of recovery of a certain amount, can also file a petition against the debtor in case his assets are not enough to pay off the debt. The insolvency laws protect the debtor from harassment by all creditors and the creditors get equitable distribution of the debtor's assets.The law on insolvency is contained in two enactments - Presidency Towns Insolvency Act, 1909 (which applies to erstwhile presidency towns of Calcutta, Madras, and Bombay of British India) and, Provincial Insolvency Act, 1920 (which applies to the whole of India except the presidency towns mentioned above). Both Acts are similar in content.Property treatmentWhen a debtor is declared insolvent, his property vests with the receiver or the official assignee (who is assigned by the court) for the purpose of distribution among the creditors.He will receive master summons from the court stating when he has to submit his tax papers, bank statements, ledger book, cheque book and all other documents that would prove his net worth.This will be handed over to the official assignee or receiver who will take charge of the assets, evaluate them and realise them for distribution.Property would include anything that is in the debtor's name - house, car, shares or any other investments that can be converted into cash. In case the debtor acquires a property, wins a lottery or receives an inheritance during insolvency proceedings and before he is discharged, even that would be used for the purpose of distribution among the creditors.Debt treatmentOnce insolvency proceedings are on, the court will publish the matter of insolvency in its official gazette and local papers so that all creditors have a chance to get their claim. If they do not come forward to claim their share, once the insolvent is discharged, he is under no obligation to pay any creditor(s).Debts that a creditor can prove to the satisfaction of the official receiver or assignee will be taken into account. There should be books of accounts and banking transactions that can prove the debt. Claims will be scrutinised for genuineness.Interest takes the last priority in the order of repayment. Moreover, it will be at the rate recognised by the court, usually around 6 per cent. In case of default in credit card payment, the court will not recognise the rate of 36-42 per cent that many credit card companies charge towards late payment, default and so on.Settlement procedureAfter deducting the court's expenses for realisation of money out of the assets, it will be distributed rateably among the unsecured creditors (who have given loans without backing of assets). The secured creditor will first have to realise the security (that is, sell the asset) and for the unrealised balance claim as an unsecured creditor out of the funds realised by the official assignee for payment.In most cases, the assets of the insolvent cannot satisfy all the debts. So the percentage of the settlement to the creditors will depend upon the amount realised by the official assignee.Take a case of an individual whose debts have mounted to Rs 1 crore (Rs 10 million), out of which Rs 30 lakhs (Rs 3 million) is secured loan. His total assets are worth Rs 40 lakh (RS 4 million) (house, car, shares and other investments). Rs 30 lakh (Rs 3 million) will be claimed by the secured creditor from the total asset value and the remaining Rs 10 lakh (Rs1 million) will be rateably distributed to all the other unsecured creditors like credit cards payments, personal loans and so on.Says T C A Shrinivasan, a Chennai-based advocate and a retired professor from Dr Ambedkar Government Law College, Chennai: "If the official assignee has reason to believe that there is scope for further payments from the debtor, then instead of an absolute discharge, only a conditional discharge will be given to the insolvent. The debtor might be directed to settle the dues out of his future earnings. These factors are, however, decided on a case-to-case basis."Disqualifications of an insolventOn being declared insolvent, you can neither be a director of a company nor a partner in a firm. You are disqualified from contesting elections or holding any public office. You are also debarred from entering into any contract or agreement. Professional bodies like the Bar Council may also prohibit you from practising if you are declared an insolvent.An insolvent will not be given credit by any public or finance institutions until the order of insolvency is set aside by the court. S. Vasudevan, senior partner at Chennai-based legal firm Vasudevan & Associates, says, "There are, however, instances where a close relative or friend may contribute for his sustenance. This may not be treated as an income of the insolvent."These disqualifications are removed when he obtains an order of discharge from the court.Back to normalTo enable one to start his life afresh, the law on insolvency provides for the discharge of an insolvent from the state of insolvency. This is the last stage of the proceedings and it releases the debtor from all the debts provable in insolvency.For this, the insolvent has to apply to the court seeking permission to annul the insolvency. Once the court is satisfied with the debt repayment, it will release him from the state of insolvency. This process, however, can be very lengthy and time-consuming.Says Vasudevan: "If an insolvent intends to resume normal life, he will have to apply to the court seeking permission to continue his livelihood and give an undertaking that out of the future earning, he would contribute to discharge the balance debt due to the debtors whose claims have not been fully settled out of the estate realised by the official assignee or receiver. The court will impose a condition that out of his monthly earnings, he must deposit a major portion towards the balance debt and that he can take a portion for his sustenance."There certainly is a lack of knowledge among debt-trapped borrowers about the recourses available to them, be it credit counselling or legal recourse. While the RBI has stepped up measures to increase awareness and formalise credit counselling in the country, very little being done on the legal front.The stigma attached to bankruptcy appears to be taking an upper hand over the recourse it offers to 'genuine' debt trapped individuals. Definitely, a defaulter cannot be rewarded for his defaults. But there has to be a mechanism to help the lender and the borrower out of their tight situation.
Q: How can i stop my father from selling property and reclaim ancestral property ?
Hi, I would like to know that the ancestral property sold by my father can be reclaimed by me or not ? Is there a way to put pressure on my father not to sell ancestral property further ? And, how can I ask a share in the ancestral property that has been sold ? can a father sell his ancestral property without consent of son?, My father owns ancestral property in Saharanpur(UP).
Advocate Rishabh Jain answered
From what you have stated, the answer to your question is in the negative. No. Assuming that the property you are talking about is his self acquired property, you can not stop him from selling his propertiesTill the time your father is alive you cannot ask for share in ancestral property
Q: How to check registered will online if registered will is true or not ?
Plaintiff grand father have executed a rigster will on 1953 of immovable property all are accepting .changing a Khaata also and sale the property of me in 1994.but the plaintiff have chance the version their is no any will its only a gift deed is an register. I the purchaser of the property how to prove the rigister will. what is the supreme court judgement on registered will.
Advocate Rishabh Jain answered
Registration of a WILL by the testator only provides evidence that proper parties appeared before the registering officer and that the officer attested the same after duly ascertaining their identity. However,Registration accords no special sanctity to the WILL. Registered or otherwise a WILL must be proved as duly and validly executed as required under Indian Succession Act. In the given situation,namely,non- acceptance of the WILL by the relative, the aggrieved son(the beneficiary)may apply to competent Court for grant of Probate. A Probate granted by Court forms conclusive evidence of the validity of the WILL.
Q: can recovery agent visit your house on sunday to ask for pending money is it legal
I wanted to know that if there is credit card amount pending with bank, can bank representative visit home and ask for the amount. Are they authorized? can recovery agent visit my house on sunday? can recovery agent visit your house without permission
Advocate Rishabh Jain answered
wanted to know that if there is credit card amount pending with bank, can bank representative visit home and ask for the amount. Are they authorized?Response Yes they can and they can send you notices. If you are having any trouble regarding the same you can tell me I can help you with the same.
Frequently Asked Questions about Advocate Rishabh Jain
Can Advocate Rishabh Jain represent me in court?
Yes, Advocate Rishabh Jain can represent you in court. The lawyer is trained to present your case in the most effective way possible.
What should I bring to my initial consultation with Advocate Rishabh Jain?
When you meet with Advocate Rishabh Jain for an initial consultation, it is important to bring any relevant documents or information with you. This may include documents related to your legal issue, such as contracts or court orders, as well as any other relevant information, such as a list of questions or concerns you have about your case.
How do I prepare for my initial consultation with Advocate Rishabh Jain?
Before your initial consultation with Advocate Rishabh Jain, it can be helpful to think about the specific legal issue you are facing and any questions or concerns you have about your case. You should also gather any relevant documents or information that you think may be helpful in understanding your situation.
What should I expect during my initial consultation with Advocate Rishabh Jain?
During your initial consultation with Advocate Rishabh Jain, you can expect to discuss the specific legal issue you are facing and the details of your situation. Lawyer will ask you questions to get a better understanding of your case and will provide you with information about your legal options and any potential outcomes.
How do I communicate with Advocate Rishabh Jain?
It is important to communicate with Advocate Rishabh Jain regularly to stay updated on the progress of your case and to discuss any new developments or concerns you may have. You can communicate with the lawyer through phone calls, emails, or in-person meetings.
How much does it cost to hire Advocate Rishabh Jain?
The cost of hiring Advocate Rishabh Jain can vary widely. Some lawyers charge hourly rates, while others charge a flat fee for their services. Some also offer free initial consultations to discuss your case. Kindly contact the lawyer directly to enquire about the fee.